FSCA Regulatory Warning: How Unregistered Funeral Parlours Collect Illegal Insurance Premiums
The Financial Sector Conduct Authority continues enforcement against unaccredited undertakers operating self-underwritten policies without registered life insurance underwriters.
By FIPSA Admin
Summary of Inquiry & Key Findings
The difference under South African law between a funeral service contract and an underwritten financial policy.
FSCA requirements: Every commercial parlour offering insurance benefits must be underwritten by a licensed life insurer.
Common non-compliance: Unregistered undertakers pocketing monthly cash payments without financial reserves.
Official FSCA verification tools available for policyholders to check FSP license status online.
The FSCA’s Ongoing Industry Oversight
The Financial Sector Conduct Authority (FSCA) regularly issues public cautionary notices regarding funeral undertakers across Gauteng, KwaZulu-Natal, and the Eastern Cape who collect monthly policy premiums without statutory authorization.
Under the Insurance Act (Act 18 of 2017) and the Financial Advisory and Intermediary Services (FAIS) Act (Act 37 of 2002), operating an insurance scheme without an authorized life underwriter (such as Sanlam, Old Mutual, Guardrisk, or Safrican) constitutes a criminal offence.
Statutory Rule: Insurance Act (Act 18 of 2017)
No entity may conduct insurance business in South Africa without being licensed by the Prudential Authority. Funeral parlours that "self-underwrite" by holding premiums in private accounts face statutory fines up to R10 million and criminal prosecution.
Risks to Bereaved Families During Claims
When an unaccredited parlour self-underwrites, there are no capital adequacy reserves backing the consumer’s policy. If multiple claims occur within a short window—or if the business owner faces financial distress—bereaved families are frequently told their policies have "lapsed" or are forced to pay cash upfront for burial services.
The FSCA advises all policyholders to confirm that their monthly policy documents clearly specify the name of the licensed underwriter and include a direct claim telephone number.
How Consumers Can Verify Policy Validity
Examine your policy schedule: Look for the name and FSP number of the registered life insurer underwriting the policy.
Visit the FSCA online search tool (www.fsca.co.za) to confirm if the FSP number is active and in good standing.
Contact the named underwriter directly to verify that your specific policy number has been registered on their master register.
Insist on printed receipts, debit order traces, or official bank notifications for all monthly premium payments.
Published by FIPSA Admin
Compiled for public education and industry reference in terms of the National Health Act (GN R363) and statutory funeral regulations in South Africa.Related Industry Dispatches
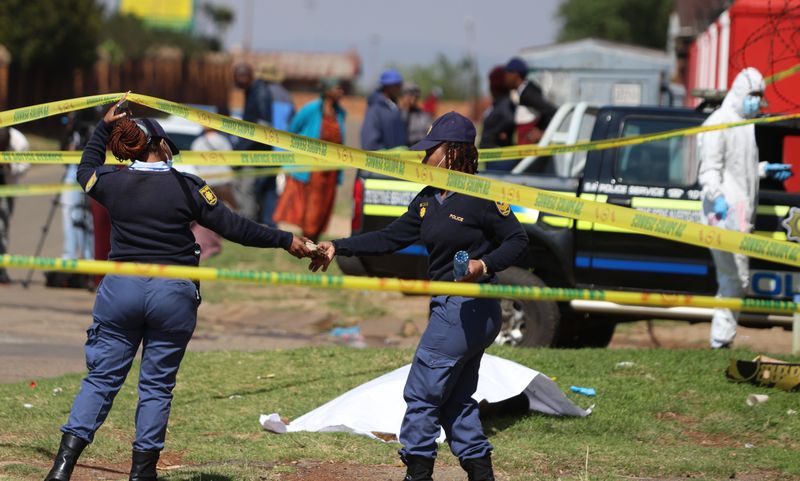
Gauteng Police Probe: Five Bodies Recovered in Kempton Park Cluster & The State Mortuary Process
Between July and September 14, 2026, the bodies of five women were recovered in the Kempton Park and Olifantsfontein areas of Gauteng. All remains were transferred to the Germiston Forensic Pathology Service mortuary for formal identification.
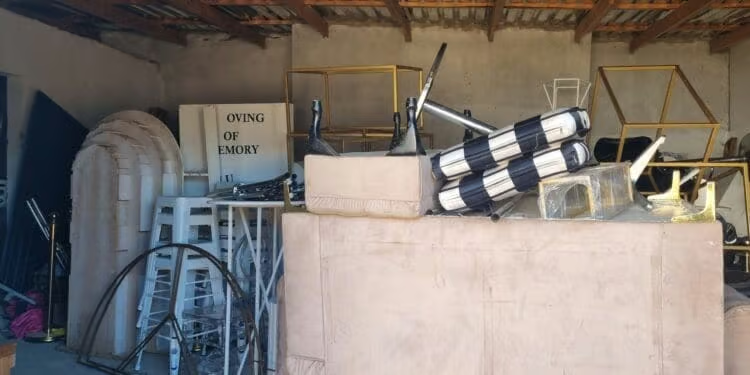
City of Joburg Shuts Down Illegal Ennerdale Undertaker Storing Bodies in Domestic Freezer
In May 2026, the City of Johannesburg officially shut down an illegal funeral undertaker in Ennerdale Extension 6 after discovering two deceased bodies stored inside a standard chest freezer without municipal health certificates.
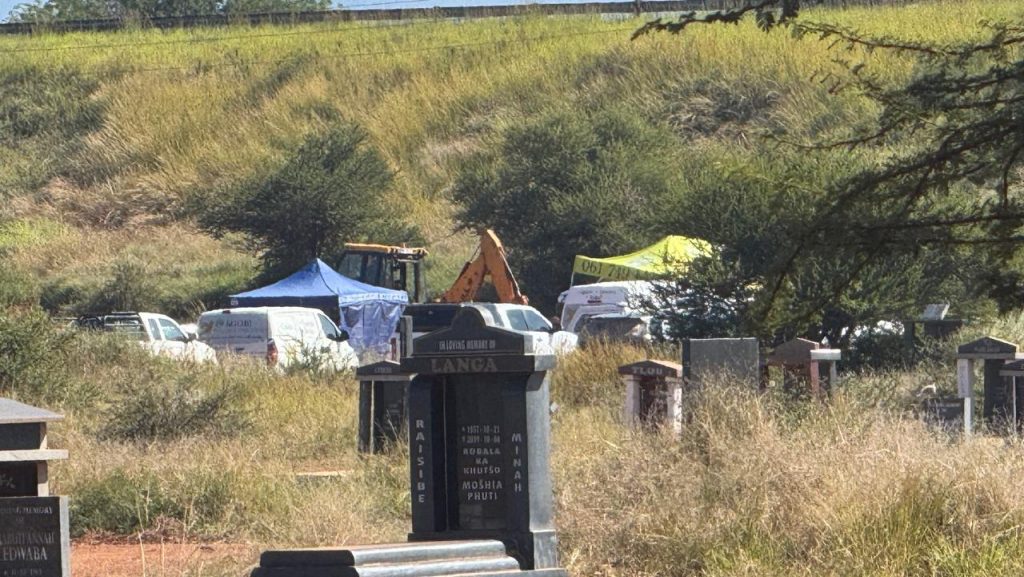
Limpopo Health Department Exhumations: The Mookgophong Mass Pauper Graves Investigation
In May 2025, authorities in Limpopo initiated the exhumation of approximately 40 bodies buried without coffins in two mass graves at Mookgophong cemetery. The Limpopo Department of Health launched an investigation into the contracted funeral parlour.